About
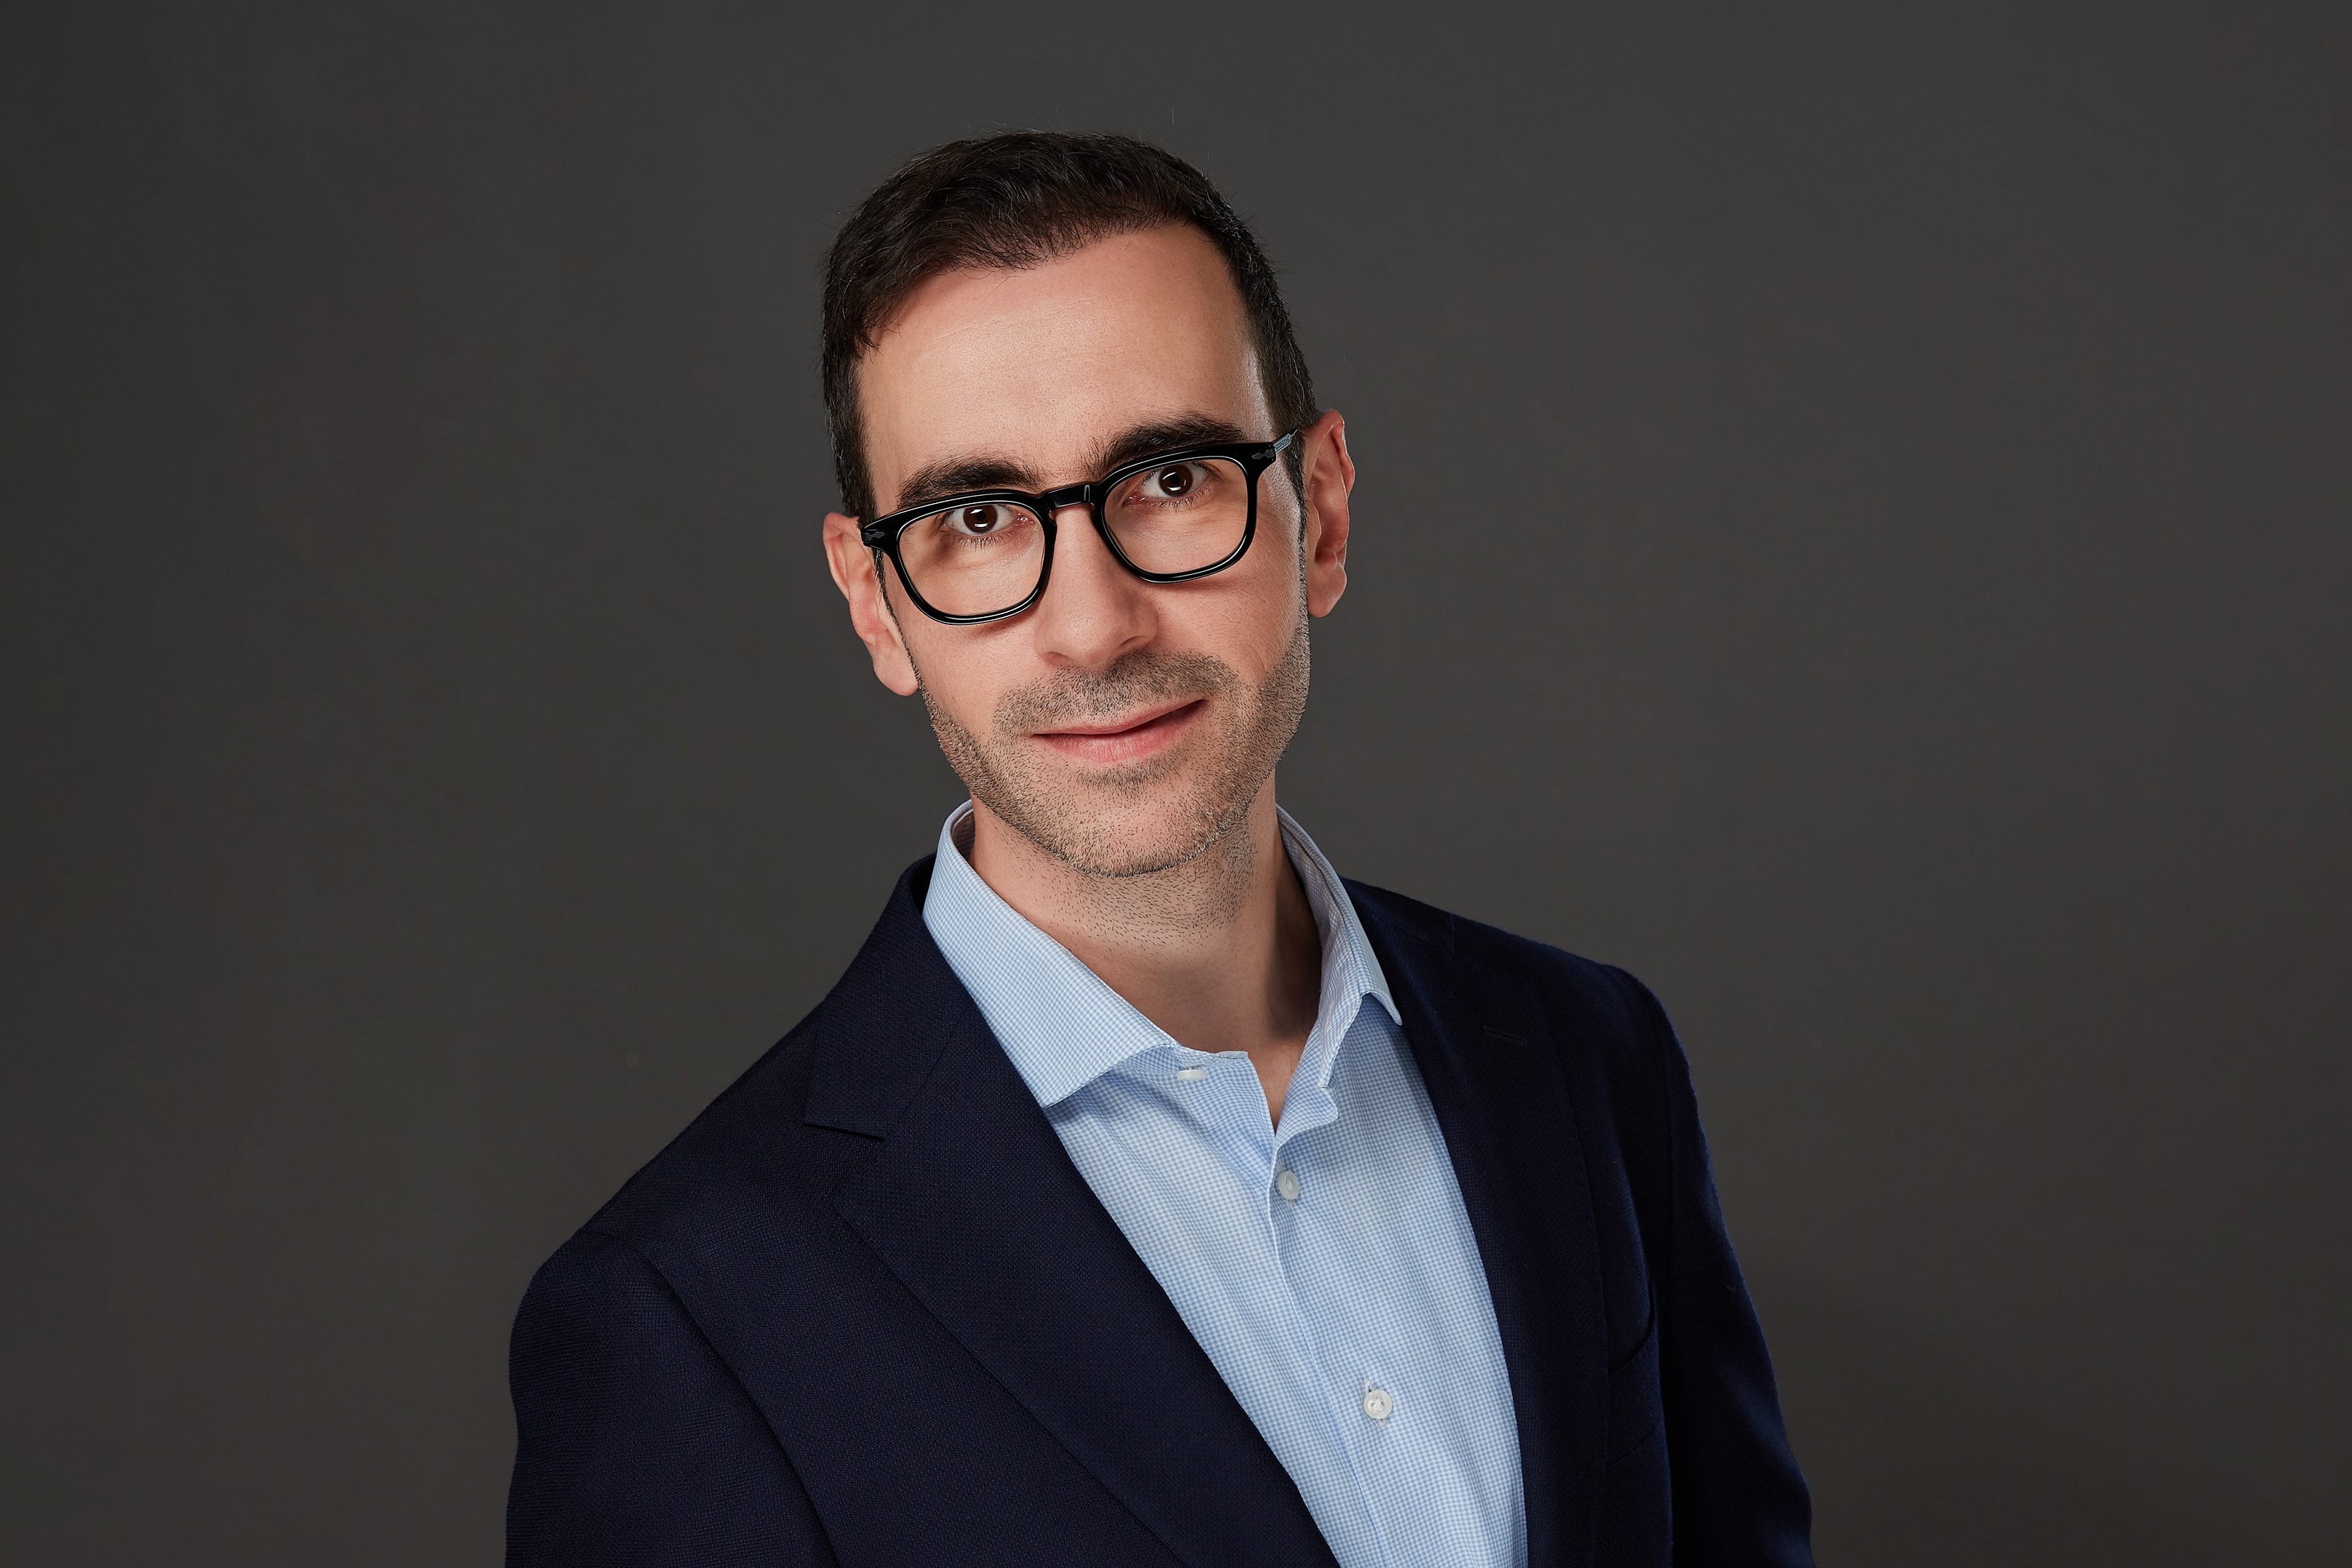
Ugur Hasdemir: Independent S/4HANA Finance Architect
I make sure the financial truth matches the operational reality. For 15+ years I have worked in SAP Finance, designing and validating S/4HANA Finance for global manufacturers, utilities, and logistics businesses, and I do it independently of any System Integrator.
Independent S/4HANA Finance Architect · Utrecht, Netherlands · SAP Press author
What I do
I am a Finance-first design validator. While System Integrators build to the spec they are given, I check whether the spec is right: enterprise structure, ledger and group valuation, margin analysis, product costing, intercompany, allocations, and the close. When the design is sound, programs avoid the expensive rework that surfaces after go-live.
Track record
I have led Finance design on enterprise S/4HANA programs, including Content Lead for the Accounting and Controlling streams of a major European utility's next-generation ERP program, with key design decisions spanning ledger models, segment and profit-center design, margin analysis, overhead cost accounting, value flows and settlements, and intercompany billing. My work has supported finance transformations at organizations including Unilever, Air France-KLM, Cargill, and LeasePlan.
Credibility
I am an SAP Press and Rheinwerk author, and I write regularly at s4hanablog.com on the design decisions that make or break S/4HANA Finance.
How I work
Independent, vendor-neutral, and direct. I tell you what I see, not what is comfortable. I am based in Utrecht and work with programs across the Netherlands and DACH.
What I check
The parts of the Finance design where programs lose data integrity and only find out at the first close. Most of those postings are not made by Finance. They come from logistics, sales, procurement, production and projects, and most Finance teams only review their own corner. I check the whole value flow.
Enterprise structure and chart of accounts
The frame everything else hangs on: company codes, plants, sales and purchasing organisations on the logistics side; controlling area, operating concern, profit centers, segments and functional areas on the Finance side; and one chart of accounts that serves group reporting and local statutory needs. Get this wrong and every later fix is a migration.
What I check
- Company code, plant, controlling area and operating concern assignments against the legal and the management structure
- One operational chart of accounts, with group and country charts where local GAAP needs them, account groups, and the account types for primary and secondary costs
- Profit center and segment design that follows how the business is steered, not the material master
- Functional areas for cost of sales reporting and the dimensions every planned report needs
Finance integration with logistics, sales, procurement, production and projects
Most postings in the Universal Journal are created by goods movements, invoices, deliveries, confirmations and settlements in MM, SD, PP, PS and PM/CS, not by Finance. Programs leave this to the logistics workstreams and find out at the first close that inventory, cost of sales and the P&L do not agree. This is where I spend most of my review time.
What I check
- Account determination for goods movements, invoice verification and billing, valuation classes, price control per material type, and GR/IR clearing
- Procure to pay: purchase order account assignment, invoice variances, accruals, and consignment and subcontracting flows
- Order to cash: pricing conditions to revenue and deduction accounts, event-based revenue recognition for sales orders, projects and services, and the cost of goods sold split
- Production, plant maintenance and projects: order types, work in process, variance categories, results analysis and settlement rules for production, PM/CS and WBS elements
- Cut-over: how open purchase orders, sales orders, production orders and inventory values migrate with their Finance values intact
General Ledger and ledgers (FI-GL)
The Universal Journal is one table; the ledgers on top of it decide what each stakeholder sees. Parallel accounting for IFRS and local GAAP, the leading and non-leading ledgers, extension ledgers, and the currencies and fiscal year variants each ledger carries.
What I check
- Leading and non-leading ledgers, extension ledgers for management adjustments, and the accounting principle each one carries
- Currency types per ledger and company code, with group and functional currencies where consolidation and reporting need them
- Fiscal year variants, posting periods and the close steps that depend on them: foreign currency valuation, reclassification, accruals
- Open item management, clearing and the period-end sequence, so the close is a schedule rather than a search
Document splitting and Profit Center Accounting
Document splitting is what makes a balance sheet by profit center or segment possible, and it is close to impossible to change after go-live. The characteristics, the zero-balance rules and the profit center derivation decide whether segment reporting is real or a reconciliation exercise every month.
What I check
- Splitting characteristics, with the zero-balance and mandatory settings per characteristic
- Item categories, business transaction variants and constants for the document types that carry the split: invoices, payments, clearings
- Profit center derivation from material, cost object, sales order and asset, with the defaults and substitutions that catch the rest
- Migration of open items with document splitting active, so the first balance sheet by segment reconciles
Margin Analysis (CO-PA)
Margin Analysis lives in the Universal Journal, so the design is about which characteristics and derivations exist and how cost reaches the margin. The question is whether margin reporting matches how the business sells and steers: by customer, product, channel, region or project.
What I check
- Operating concern, characteristics and derivation rules from the customer master, the material master and the sales order
- Cost of goods sold split by cost component, and the attribution of price differences and production variances to the margin
- How overhead reaches the margin: top-down distribution, assessment to profitability segments, and the realignment strategy
- Account-based Margin Analysis as the basis, and what, if anything, still needs costing-based CO-PA next to it
Product Costing and Material Ledger (CO-PC)
Standard costs set inventory values and the margin; actual costing decides whether the P&L shows what production really cost. Costing variants, the cost component structure and the Material Ledger are where manufacturers find the surprises at the first close.
What I check
- Costing variants, valuation variants, the costing sheet for overhead and the cost component structure
- Price control per material type, Material Ledger activation and the actual costing run
- Work in process, variance categories and settlement of production and process orders
- Co-products, by-products, subcontracting and intercompany stock transfers, including group valuation and transfer prices where they apply
Overhead Controlling and allocations (CO-OM, PaPM)
Cost centers, internal orders and the allocation cycles that move cost to where the business wants to see it. When allocations get complex, SAP Profitability and Performance Management (PaPM) takes over, and the design has to say what runs where and how the two reconcile.
What I check
- Cost center standard hierarchy, cost center categories, activity types and the planning approach
- Assessment, distribution and activity allocation cycles, sender and receiver rules, and their run order in the close
- Internal orders and statistical orders, settlement rules and receivers
- Which allocations run in universal allocation and which in PaPM, with the reconciliation between them
Asset Accounting (FI-AA) and Investment Management
Asset Accounting posts per ledger, so depreciation areas must line up with the accounting principles. Capitalisation rules, assets under construction, investment orders and projects decide how CAPEX reaches the balance sheet and how it is reported before it does.
What I check
- Chart of depreciation, depreciation areas per ledger and accounting principle, and the posting of parallel valuations
- Asset classes, account determination, capitalisation thresholds and low-value asset rules per country
- Assets under construction, investment orders and WBS elements with settlement to fixed assets
- Investment programs and budgeting where Investment Management is in scope, and intercompany asset transfers
Intercompany billing, reconciliation (ICMR) and group reporting
Intercompany is where most closes lose days. The value flows between company codes, intercompany billing, matching and reconciliation, and the feed to group consolidation decide whether the group close is a process or a rescue.
What I check
- Intercompany scope: stock transfers, drop shipments, services, cost and asset transfers, with pricing and tax treatment per flow
- Intercompany billing and the partner assignment on every intercompany posting, so eliminations work
- Matching and reconciliation (ICMR) rules, matching methods and the reconciliation calendar inside the close
- The feed to SAP Group Reporting or the consolidation system: financial statement items, consolidation units and the mapping
Enterprise structure and chart of accounts
The frame everything else hangs on: company codes, plants, sales and purchasing organisations on the logistics side; controlling area, operating concern, profit centers, segments and functional areas on the Finance side; and one chart of accounts that serves group reporting and local statutory needs. Get this wrong and every later fix is a migration.
What I check
- Company code, plant, controlling area and operating concern assignments against the legal and the management structure
- One operational chart of accounts, with group and country charts where local GAAP needs them, account groups, and the account types for primary and secondary costs
- Profit center and segment design that follows how the business is steered, not the material master
- Functional areas for cost of sales reporting and the dimensions every planned report needs
Finance integration with logistics, sales, procurement, production and projects
Most postings in the Universal Journal are created by goods movements, invoices, deliveries, confirmations and settlements in MM, SD, PP, PS and PM/CS, not by Finance. Programs leave this to the logistics workstreams and find out at the first close that inventory, cost of sales and the P&L do not agree. This is where I spend most of my review time.
What I check
- Account determination for goods movements, invoice verification and billing, valuation classes, price control per material type, and GR/IR clearing
- Procure to pay: purchase order account assignment, invoice variances, accruals, and consignment and subcontracting flows
- Order to cash: pricing conditions to revenue and deduction accounts, event-based revenue recognition for sales orders, projects and services, and the cost of goods sold split
- Production, plant maintenance and projects: order types, work in process, variance categories, results analysis and settlement rules for production, PM/CS and WBS elements
- Cut-over: how open purchase orders, sales orders, production orders and inventory values migrate with their Finance values intact
General Ledger and ledgers (FI-GL)
The Universal Journal is one table; the ledgers on top of it decide what each stakeholder sees. Parallel accounting for IFRS and local GAAP, the leading and non-leading ledgers, extension ledgers, and the currencies and fiscal year variants each ledger carries.
What I check
- Leading and non-leading ledgers, extension ledgers for management adjustments, and the accounting principle each one carries
- Currency types per ledger and company code, with group and functional currencies where consolidation and reporting need them
- Fiscal year variants, posting periods and the close steps that depend on them: foreign currency valuation, reclassification, accruals
- Open item management, clearing and the period-end sequence, so the close is a schedule rather than a search
Document splitting and Profit Center Accounting
Document splitting is what makes a balance sheet by profit center or segment possible, and it is close to impossible to change after go-live. The characteristics, the zero-balance rules and the profit center derivation decide whether segment reporting is real or a reconciliation exercise every month.
What I check
- Splitting characteristics, with the zero-balance and mandatory settings per characteristic
- Item categories, business transaction variants and constants for the document types that carry the split: invoices, payments, clearings
- Profit center derivation from material, cost object, sales order and asset, with the defaults and substitutions that catch the rest
- Migration of open items with document splitting active, so the first balance sheet by segment reconciles
Margin Analysis (CO-PA)
Margin Analysis lives in the Universal Journal, so the design is about which characteristics and derivations exist and how cost reaches the margin. The question is whether margin reporting matches how the business sells and steers: by customer, product, channel, region or project.
What I check
- Operating concern, characteristics and derivation rules from the customer master, the material master and the sales order
- Cost of goods sold split by cost component, and the attribution of price differences and production variances to the margin
- How overhead reaches the margin: top-down distribution, assessment to profitability segments, and the realignment strategy
- Account-based Margin Analysis as the basis, and what, if anything, still needs costing-based CO-PA next to it
Product Costing and Material Ledger (CO-PC)
Standard costs set inventory values and the margin; actual costing decides whether the P&L shows what production really cost. Costing variants, the cost component structure and the Material Ledger are where manufacturers find the surprises at the first close.
What I check
- Costing variants, valuation variants, the costing sheet for overhead and the cost component structure
- Price control per material type, Material Ledger activation and the actual costing run
- Work in process, variance categories and settlement of production and process orders
- Co-products, by-products, subcontracting and intercompany stock transfers, including group valuation and transfer prices where they apply
Overhead Controlling and allocations (CO-OM, PaPM)
Cost centers, internal orders and the allocation cycles that move cost to where the business wants to see it. When allocations get complex, SAP Profitability and Performance Management (PaPM) takes over, and the design has to say what runs where and how the two reconcile.
What I check
- Cost center standard hierarchy, cost center categories, activity types and the planning approach
- Assessment, distribution and activity allocation cycles, sender and receiver rules, and their run order in the close
- Internal orders and statistical orders, settlement rules and receivers
- Which allocations run in universal allocation and which in PaPM, with the reconciliation between them
Asset Accounting (FI-AA) and Investment Management
Asset Accounting posts per ledger, so depreciation areas must line up with the accounting principles. Capitalisation rules, assets under construction, investment orders and projects decide how CAPEX reaches the balance sheet and how it is reported before it does.
What I check
- Chart of depreciation, depreciation areas per ledger and accounting principle, and the posting of parallel valuations
- Asset classes, account determination, capitalisation thresholds and low-value asset rules per country
- Assets under construction, investment orders and WBS elements with settlement to fixed assets
- Investment programs and budgeting where Investment Management is in scope, and intercompany asset transfers
Intercompany billing, reconciliation (ICMR) and group reporting
Intercompany is where most closes lose days. The value flows between company codes, intercompany billing, matching and reconciliation, and the feed to group consolidation decide whether the group close is a process or a rescue.
What I check
- Intercompany scope: stock transfers, drop shipments, services, cost and asset transfers, with pricing and tax treatment per flow
- Intercompany billing and the partner assignment on every intercompany posting, so eliminations work
- Matching and reconciliation (ICMR) rules, matching methods and the reconciliation calendar inside the close
- The feed to SAP Group Reporting or the consolidation system: financial statement items, consolidation units and the mapping
Find your finance design risks before your auditors do.
The free Finance Readiness Assessment scores your design across five categories in about 15 minutes, with an instant dashboard. No charge, no waiting.